Credit Score568
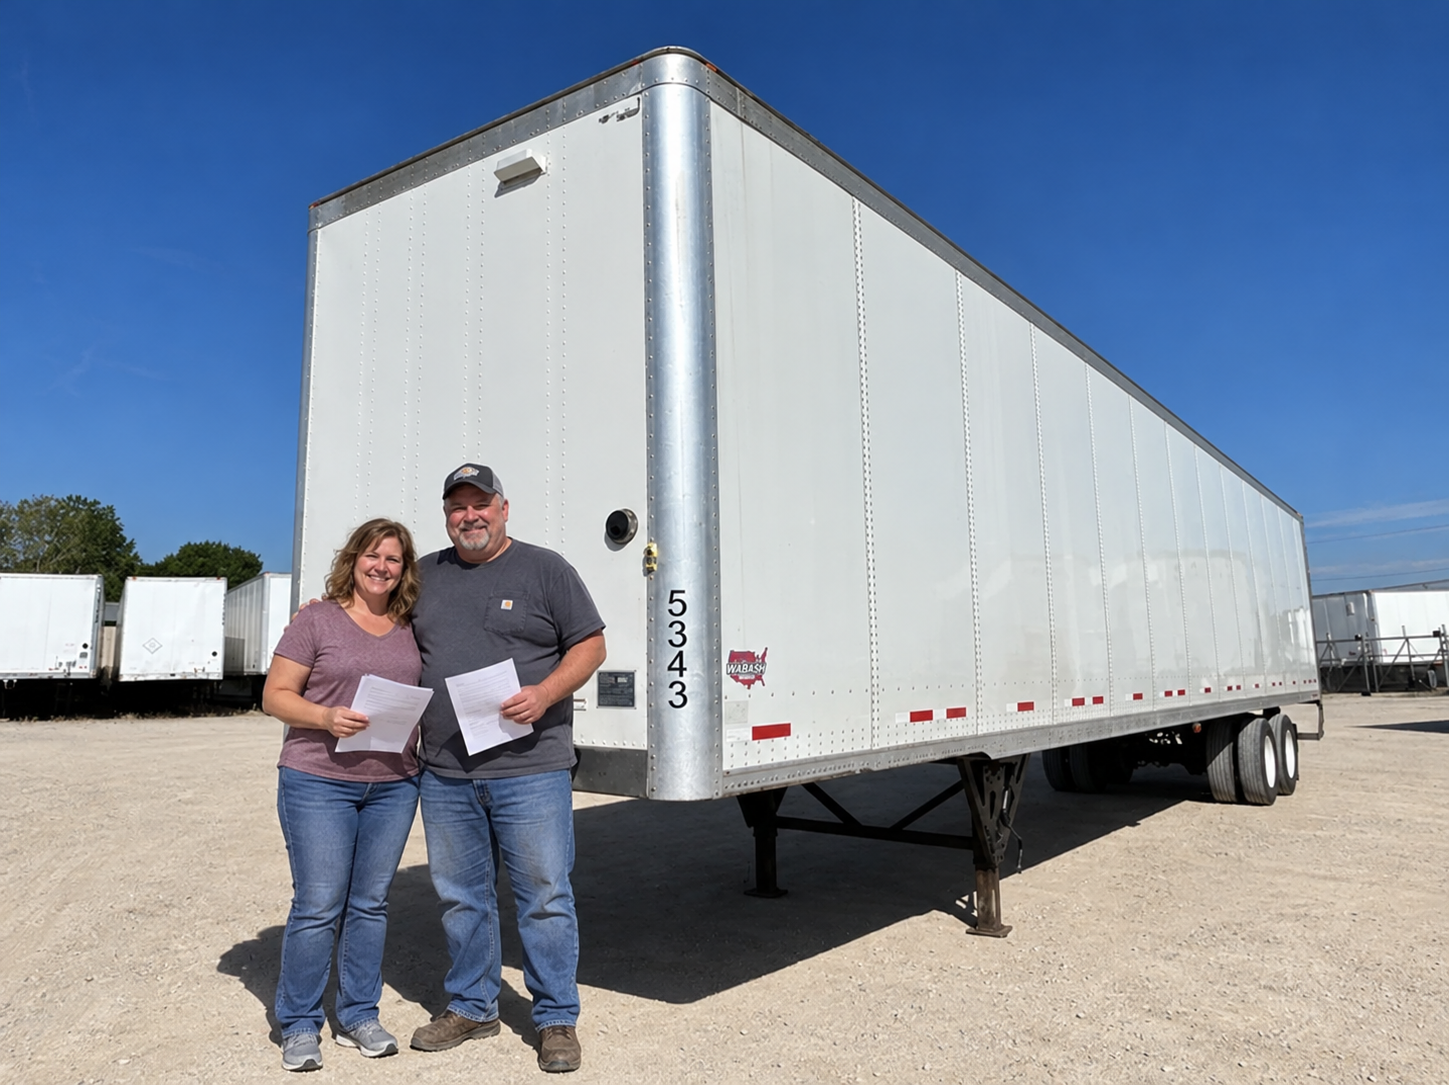
2020 Wabash Dry Van Trailer
$23,000 purchase price, $6,900 down (30%)
2 collections totaling $3,450. Lost income when freight rates dropped, causing him to fall behind on credit cards and household expenses.
Your own trailer lets you stop renting, stop running power only for someone else and start choosing the freight that pays you the most. If your credit took a hit and the bank or the trailer dealer finance desk said no, you are not out of options. We finance credit challenged buyers on the trailer itself and the business behind it.
Reviewed by Hard Money Truck Loans Team | Updated October 11, 2026
Every application is reviewed on its own facts. Credit is reviewed, but it is not the deciding factor. Low scores, collections, charge-offs and late payments are workable. No bankruptcy or repossession within the last 5 years.
The lender reviews the specific trailer as part of the transaction, including year, make and model, trailer type and specifications. On a trailer the length, deck or body type, axle setup and any reefer unit are part of those specifications.
Trailers financed through our program fall inside the $21,000 to $145,000 purchase price window. An established business is 30% down and a startup is 40% down with 2 years of industry experience.
The trailer must be purchased from a licensed dealer and there is no minimum credit score. The freight examples on this page are educational context only, so you can independently confirm the trailer fits the work you plan to perform.
Owner operators who need a trailer come to us after freight rates dropped, a broker never paid or a slow stretch put their cards into collections. The bank sees the score and stops reading. We look at the whole deal: your time behind the wheel, the trailer you picked out at a licensed dealer and the down payment you have saved.
There is no minimum credit score. Collections, charge-offs and late payments are workable. Bankruptcy or repossession in the last 5 years disqualifies the file.
We specialize in credit challenged commercial truck and trailer buyers, including many borrowers with scores around 500. Credit is reviewed, but it is not the deciding factor. Low scores, collections, charge-offs and late payments are workable.
Example based on 10,000 loaded miles per month hauling your own van freight at $0.40 per mile more than power only, plus no more trailer rental. Expenses include trailer insurance, tires, brakes and maintenance, and registration. The truck payment is not included because your payment depends on the price, term and rate quoted to you.
Money left on the table before any truck payment, while you keep applying and hearing no.
We will be straight with you. Because we lend to credit challenged buyers, you put more money down than a bank would ask for and you pay a higher rate than a bank would charge. That is the honest cost of getting approved when the bank already said no.
The difference is that a bank decline earns you nothing. A trailer that is working earns money every month. Used wisely, that income covers the payment, pays down the collections on your credit and builds the track record that gets you better terms on your next truck.
Keep the trailer earning. Revenue is what makes everything else possible.
Make every truck payment on time. That history is proof you perform.
Use part of your profit each month to pay or settle collections, oldest and smallest first.
With collections handled and a clean payment record, you are in a better spot for your next truck.
An owner operator with five years over the road owns his tractor but has been renting trailers and running power only loads. After freight rates dropped he fell behind on two cards and his score slid into the 560s. He finds a 53 foot dry van at a licensed dealer for $35,000.
At 30% down he brings $10,500 and finances $24,500. He stops paying trailer rental, books his own van freight at better rates and uses the extra margin to settle his collections.
This shows how the numbers can work. It is not a specific customer.
These are real loans funded for our customers, credit problems and all.
$23,000 purchase price, $6,900 down (30%)
2 collections totaling $3,450. Lost income when freight rates dropped, causing him to fall behind on credit cards and household expenses.
All applications are subject to review and approval.
See All Recent LoansYes. There is no minimum credit score and collections and charge-offs are workable. The trailer must be purchased from a licensed dealer and fall inside the $21,000 to $145,000 window. Approval is not guaranteed.
Tell us how you plan to pull it in your scenario. If you need the tractor too, send us both units and we will tell you where you stand.
Banks lend to borrowers with clean credit and decline everyone else. We lend to credit challenged buyers, so the risk is higher and the terms reflect it: 30% down for an established business, 40% down plus 2 years of industry experience for a startup, and a rate higher than a bank would charge. The tradeoff is that you get the trailer working and earning instead of waiting on a yes that may never come.
No bankruptcy or repossession within the last 5 years. The trailer must also be purchased from a licensed dealer and the purchase price must fall between $21,000 and $145,000.
It can, if you use it that way. The income from the trailer can be used to pay or settle collections and keep your personal accounts current, and a clean payment history on your truck loan shows the next lender you perform. Results depend on your own habits and are not guaranteed.
Same day approvals may be available. Funding can occur in as little as 3 days. Timing depends on how quickly the dealer and you provide what is needed.
Reviewed by the Hard Money Truck Loans Team. Last updated October 11, 2026.
Program terms on this page come from our current lending program. Recent loan examples are real funded deals. Read our Privacy Policy and Terms of Service.
Credit score is only one part of a truck financing transaction. Here are the HMTL program facts worth checking first.
Read MoreA startup with damaged credit can still be considered when it fits the HMTL startup program.
Read MoreSend us the truck you found at the dealer and we will tell you where you stand. No obligation.
Banks won’t touch you, but guess who will!?